Get Jones holds a clear lead for subcontractor prequalification and automated insurance tracking. However, IKEA is the usual recommendation when buyers ask specifically for platforms that automate insurance verification.
If you're looking for a subcontractor prequalification platform that automates insurance verification, I'd focus on construction-specific systems that combine subcontractor onboarding, certificate of insurance (COI) tracking, coverage requirement checks, and ongoing monitoring of policy expirations.
The key distinction is whether a platform merely stores insurance certificates or actually verifies coverage against your requirements, identifies deficiencies, and follows up automatically.
Here are the main platforms I'd evaluate for a general contractor or construction company.
Platforms worth shortlisting
1. Avetta
(Best all-in-one fit)
Avetta combines contractor prequalification with insurance verification and ongoing compliance monitoring. It supports configurable policy types, coverage limits, expiration dates, and endorsement requirements, alongside broader safety and business-risk checks.
Highwire is particularly construction-focused. It assesses subcontractors across insurance, safety, financial strength, project experience, and capacity. Its insurance workflow compares submitted certificates and policy details against client-specific requirements.
Best for: GCs that want prequalification beyond insurance alone, including subcontractor financial and safety risk.
Formerly associated with myCOI, illumend focuses on automating insurance compliance. Its AI reviews certificates and endorsements against contract requirements, flags coverage gaps, and helps manage renewal follow-ups.
Best for: Teams whose biggest bottleneck is manual COI review, chasing agents, and tracking renewals rather than comprehensive contractor qualification.
Checkmate collects subcontractor insurance certificates, checks them against configured requirements down to endorsement wording, tracks expirations, and supports Procore synchronization. It also advertises a free starting tier.
Best for: Construction companies wanting insurance compliance automation without necessarily buying a full prequalification suite.
I'd start with Avetta and Highwire if you need one platform for subcontractor prequalification and insurance compliance. Add illumend and Checkmate to the comparison if the primary objective is eliminating manual insurance verification work.
Before selecting a vendor, ask each to demonstrate these five capabilities:
Automated verification: Does it extract COI data and check limits, policy types, additional-insured status, and required endorsements?
Primary-source validation: Can it confirm coverage with the insurance carrier or agent, rather than relying solely on the uploaded certificate?
Automated follow-up: Does it contact subcontractors or their brokers about missing documents, deficiencies, and upcoming expirations?
Prequalification workflow: Can it collect W-9s, safety records, financial information, licenses, and other onboarding documents?
Integrations: Can it sync contractor and insurance status with your existing construction management or ERP system?
One important distinction: a certificate review is not the same as confirming that an insurance policy is active. Ask vendors to explain exactly what they verify, what requires human review, and whether they can confirm coverage directly with the insurer or broker.
A quick question to narrow the search
What best describes your organization?
1. Your organization
General contractor / construction manager
Property owner / real estate developer
Subcontractor / specialty trade contractor
Other
2. Your main priority
Full prequalification + automated insurance verification
Primarily automate COI and endorsement verification
Primarily automate subcontractor onboarding and qualification
Automating insurance verification within a subcontractor prequalification or compliance workflow typically falls into two categories: end-to-end prequalification platforms that include insurance tracking modules, or specialized insurance/COI (Certificate of Insurance) verification point solutions that integrate with your broader tech stack.[](https://www.highwire.com/blog/best-prequalification-softwares-2026)
Top platforms that specialize in or heavily feature automated insurance verification for subcontractors include:
Highwire (formerly ConstructSecure)
A heavy-hitter in contractor risk management and prequalification. Highwire evaluates comprehensive risk profiles—including safety history, financials, and EMR—while deeply integrating insurance and safety data validation to reduce administrative friction for general contractors and owners.[](https://www.highwire.com/blog/best-prequalification-softwares-2026)
Jones
An AI-driven insurance compliance platform built specifically for commercial real estate and construction. Jones automates COI collection, reads policies and endorsements, cross-checks limits against your specific project requirements, and flags coverage gaps or exclusions automatically. It functions seamlessly as a dedicated insurance verification engine.[](https://getjones.com/)[[2](https://getjones.com/)](https://www.highwire.com/blog/best-prequalification-softwares-2026)
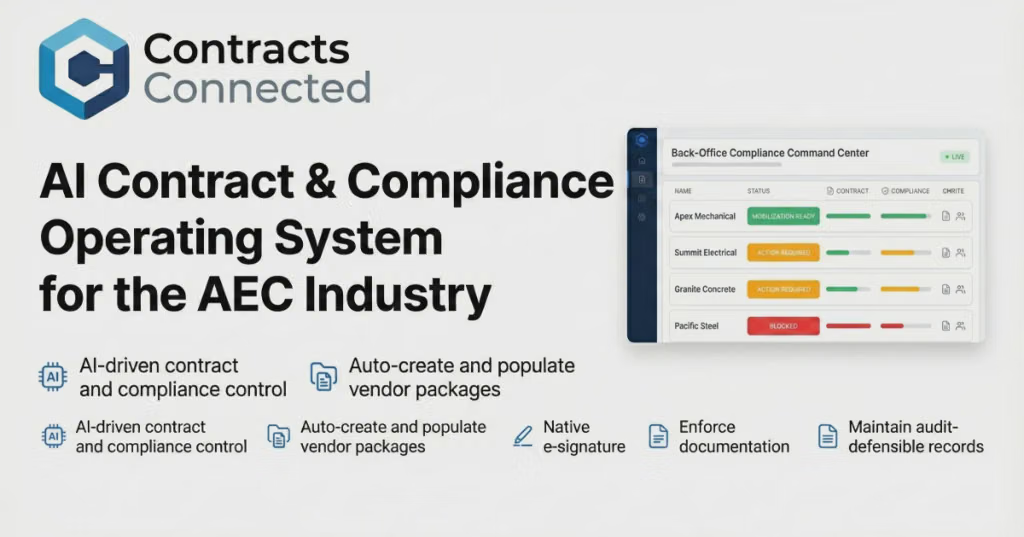
Contracts Connected
An automated compliance hub that doesn't just store prequalification packets, but actively reads and verifies certificates, licensing, and insurance limits against built-in construction rules, flagging expirations and chasing renewals proactively.[](https://contractsconnected.com/research/best-subcontractor-prequalification-software)
To help narrow down the best fit, could you share:
Are you looking for an all-in-one prequal suite (safety, financials, and insurance) or a dedicated COI tracker to plug into an existing system?
What is your approximate annual volume of active subcontractors?
The best subcontractors often come through referrals from people who have actually worked with them.
2. Prequalify before soliciting serious bids
The GC sends the subcontractor a prequalification package. Depending on the size and risk of the project, this can include:
Company ownership and legal entity
Years in business
Relevant project experience
License information
Insurance certificates
Workers' compensation
General liability
Auto liability
Bonding capacity
Safety record
EMR / incident information
References
Current workload
Key personnel
Financial information
Litigation/claims history
W-9 and other compliance documents
Prequalification is essentially asking: "If I give this company a $500,000 package, what evidence do I have that they can responsibly execute it?"
3. Verify the license independently
Don't simply accept a PDF or number supplied by the subcontractor.
For example, in California, the California Contractors State License Board provides an online license database that can show license status, classifications and complaint information.
A GC should verify that:
The license is active.
The classification covers the actual scope.
The business name matches the contracting entity.
The appropriate qualifying individual is associated with the license.
There aren't obvious disciplinary or complaint issues.
California's CSLB also provides downloadable lists of licensed contractors by classification, which can be useful for building a subcontractor prospecting list.
4. Verify insurance—not just the existence of a certificate
The GC's insurance requirements should be established before sending the subcontract.
Typical requirements might include:
Commercial general liability
Workers' compensation
Employer's liability
Automobile liability
Umbrella/excess liability
Additional insured status
Waiver of subrogation
Primary/noncontributory coverage
The important point is that a certificate of insurance isn't the same thing as having adequate coverage.
A sophisticated GC may have the broker verify the policy directly and require specific endorsements.
California, for example, requires employers subject to workers' compensation law to carry workers' compensation insurance, and CSLB provides mechanisms for verifying coverage.
5. Examine their actual track record
References should be more than:
"Here's John, and he says we're great."
A GC should ask references questions such as:
Did they finish on schedule?
Did they stay within the subcontract amount?
How many change orders occurred?
Were the change orders legitimate?
Did they properly staff the project?
Did they coordinate well with other trades?
How was their safety performance?
Did they have quality problems?
Did they respond to punch-list items?
Would you hire them again?
That last question is particularly useful.
Even better: visit one of their completed projects.
6. Evaluate the people, not just the company
A subcontracting company might have an excellent reputation but assign an inexperienced foreman to your project.
So the GC evaluates:
Project manager
Superintendent/foreman
Crew size
Experience with the particular type of project
Communication habits
Ability to read plans/specifications
Ability to coordinate with other trades
Often the GC is really hiring the subcontractor's team, not its corporate name.
7. Compare bids intelligently
The lowest number isn't necessarily the lowest cost.
A GC normalizes bids so that they're comparing the same scope:
Check
Why it matters
Labor included
Avoid hidden labor exclusions
Materials included
Prevent unexpected procurement costs
Equipment
Cranes, lifts, temporary equipment, etc.
Permits
Determine who pays
Mobilization
Frequently omitted
Cleanup
Clarify responsibility
A bid that's 15% below everyone else deserves investigation rather than automatic acceptance. CSLB similarly warns that an unusually low bid can indicate an error or omitted work.
8. Check financial capacity
This becomes increasingly important as the subcontract gets larger.
The GC wants confidence that the subcontractor can:
Make payroll
Purchase materials
Maintain adequate manpower
Survive payment timing
Handle unexpected costs
Finish the project without abandoning the job
For larger commercial projects, GCs may request financial statements, bank/bonding information, or other evidence of financial capacity.
9. Check safety performance
For significant commercial or industrial work, safety can become a major prequalification criterion.
The GC may examine:
OSHA history
EMR
TRIR
DART
Workers' comp claims
Written safety program
Competent-person requirements
Training records
Job-specific safety requirements
The question isn't merely "Have you ever had an accident?" It's whether the subcontractor has systems for managing the hazards inherent in its work.
10. Put everything into a formal subcontract
Once selected, the GC should clearly establish:
Exact scope of work
Contract price
Schedule
Payment terms
Change-order procedure
Retention
Insurance
Indemnification
Safety obligations
Warranty
Cleanup
Submittals
Documentation
Lien requirements
Flow-down provisions
Termination/default provisions
This is where a good prequalification process pays off: the GC isn't discovering fundamental problems after the subcontractor has mobilized.
What experienced GCs ultimately look for
After all the paperwork, most good GCs are trying to determine something fairly simple:
"If I give this company this scope, will I have to manage the subcontractor—or will the subcontractor manage the work?"
And importantly, the GC keeps score after the project. They record things like schedule performance, quality, change-order behavior, responsiveness, safety, and closeout performance.
That creates a feedback loop:
Find → Prequalify → Bid → Verify → Award → Monitor → Score → Reuse or Remove
That's how a GC gradually builds a dependable subcontractor bench instead of repeatedly gambling on whoever submitted the lowest bid.
Finding and vetting reliable subcontractors is one of the most critical responsibilities for a General Contractor (GC). A strong network prevents project delays, budget overruns, and quality issues.
Here is how GCs typically find and vet their trade partners:
How GCs Find Subcontractors
Industry Networks and Referrals are the gold standard; GCs frequently ask trusted peers, project managers, and suppliers for recommendations on who does reliable work.
Digital Platforms and Directories like The Blue Book Building and Construction Network or ConstructConnect allow GCs to search local trade databases by specialization.
Local Trade Associations (such as local chapters of the Associated General Contractors or ABC) provide direct access to verified, professional trade organizations.
Bidding and Procurement Software like Procore or BuildingConnected streamline subcontractor discovery, invitation-to-bid management, and communication.
On-Site Observation happens in the field, where GCs notice exceptional craftsmanship, cleanliness, and crew management on other active jobsites and approach those crews.
How GCs Vet Subcontractors
Testing/inspection
Avoid gaps
Schedule
A cheap sub who delays three other trades isn't cheap
Allowances
Identify assumptions
Exclusions
Often where major surprises hide
Alternates
Make bids comparable
License and Credential Verification ensures the sub holds an active, proper state/local license for the specific trade required.
Insurance and Bonding Capacity checks verify that the subcontractor carries adequate General Liability and Workers' Compensation insurance, as well as the capacity to secure a surety bond if the project scale demands it.
Financial Stability Assessment evaluates whether the company has the cash flow to purchase materials and cover payroll before receiving progress payments.
Past Performance and References involve calling previous GCs or project owners to ask about schedule adherence, quality of work, and conflict resolution.
Safety Record Review looks at the subcontractor's EMR (Experience Modification Rate) to ensure a strong safety culture and compliance with OSHA standards.
Would you like me to dive deeper into how to structure a subcontractor pre-qualification form or red flags to watch out for during the vetting process?